How NRIs Can Buy Property in India: A 2027 Guide
By the Valuepersqft advisory team ·
Some of our most careful clients live thousands of kilometres away. They are buying a home to retire to, a base for parents, a place for children studying in India, or simply a foothold in the city they grew up in. They are also the clients with the most questions, and rightly so: buying from abroad means trusting documents you cannot easily check, sites you cannot easily visit and rules that changed again in 2026. This guide explains how an NRI can buy property in India, step by step.
At a glance- NRIs and OCIs can buy homes, plots and commercial property, but not farmland, plantations or farmhouses.
- Pay through banking channels from abroad or from NRE, FCNR(B) or NRO accounts, never in cash.
- A specific power of attorney lets someone in India sign and register for you.
- The new Income-tax Act from April 2026 renumbered the tax rules, so let a CA handle TDS.
This guide brings those questions together in one place: what non-resident Indians and OCI cardholders can buy, how to pay, how home loans work, how to sign without flying in for every step, what tax applies, and how to take money back out later. It ends with the questions we suggest you ask any developer. Our NRI services page explains how we help clients abroad.
Who this applies to
Indian rules treat two groups of overseas buyers in much the same way for property:
- Non-resident Indians (NRIs): Indian citizens who live outside India.
- Overseas Citizens of India (OCI cardholders): foreign citizens of Indian origin who hold an OCI card. The older PIO card was merged into OCI.
Foreign nationals who are not OCIs face much tighter rules and generally cannot buy property in India without approval, so this guide does not cover them.
What NRIs can and cannot buy in India
Under India’s foreign exchange rules, NRIs and OCIs can buy residential and commercial property, and there is no limit on the number of homes. In practice that covers apartments, villas and residential plots in approved, converted layouts.
What you cannot buy is agricultural land, plantation property or a farmhouse. You can inherit them, but not purchase them. This matters more than people think around the growth corridors, where some “farm plots” and “managed farmland” schemes are sold to overseas buyers. If the land has not been converted to residential use, keep away.
A foreign spouse of an NRI or OCI can, in some cases, own one property jointly with them, subject to conditions. Ask your lawyer if that applies to you.
How to pay
Payment must come through normal banking channels, in rupees. You have two main routes:
- Money sent from abroad directly to the seller’s or developer’s Indian bank account.
- Your Indian non-resident accounts: an NRE, FCNR(B) or NRO account.
Cash, travellers’ cheques and foreign currency notes are not allowed. Keep every bank advice and remittance record. You will need them for tax, for proving the source of funds and, later, for taking sale proceeds back abroad.
A practical tip: if you think you may want to send the money back abroad one day, pay through money remitted from abroad or from your NRE or FCNR(B) account, not from NRO funds. Repatriation is simpler when the original purchase was paid in foreign exchange.
Home loans for NRIs
Most Indian banks and housing finance companies lend to NRIs for buying or building a home. Expect to provide your passport and visa or OCI card, overseas employment or business proof, salary slips or accounts, bank statements and sometimes an overseas credit report. EMIs are paid from your NRE or NRO account or by remittance. Many lenders also want a co-applicant or a local contact, and some ask for a power of attorney holder in India to handle the loan paperwork.
Loans are typically sanctioned faster for projects the bank has already approved. Ask the developer which lenders have approved the project before you apply.
Signing from abroad: power of attorney
You do not need to fly in for every step. Many of our clients sign the booking and agreement remotely and come in only for registration, and some use a power of attorney even for that.
- Draft a specific power of attorney for the property, naming a trusted person in India. Avoid a general one that gives unlimited powers.
- Sign it before an Indian embassy or consulate, or have it notarised and apostilled in the country where you live, depending on that country’s rules.
- Send the original to India. It usually needs to be stamped (adjudicated) at the local sub-registrar’s office within a set period after it arrives, often three months, before it can be used.
- The person holding the power of attorney can then sign and register documents on your behalf.
You will need a PAN card in all cases. Get it sorted early, because developers, banks and the registration office all ask for it.
Tax: what to know before you buy
India replaced its Income-tax Act of 1961 with the Income-tax Act, 2025, which came into force on 1 April 2026. The tax itself did not change much, but section numbers and form names did, so older articles online may quote outdated references. Please treat this section as a map and let a chartered accountant handle the specifics.
- Buying from a developer or a resident seller: above a set value, currently ₹50 lakh, the buyer deducts a small TDS from the payment and deposits it with the tax department.
- Buying a resale home from another NRI: the buyer must deduct tax on the seller’s capital gains at higher rates. This is the step most often missed. Get your CA involved before you pay.
- Rental income: rent from your Indian property is taxed in India, and tenants are required to deduct tax before paying rent to an NRI landlord. You may get credit in your country of residence under a tax treaty.
- Selling later: capital gains tax applies in India. Tax will be deducted from the sale proceeds, and you can claim a refund if too much was withheld.
Taking money back out: repatriation
Most NRIs want to know they can move money abroad again if they sell. The broad rules are:
- For residential property bought with foreign exchange, you can repatriate the sale proceeds for up to two such properties, up to the amount originally paid in foreign exchange.
- From your NRO account, you can remit up to USD 1 million per financial year, covering sale proceeds and other balances, with a chartered accountant’s certificate and the required forms.
- Amounts above these limits need approval from the Reserve Bank of India.
The paperwork for sending money abroad also changed with the new tax law in 2026, so check the current forms with your bank and CA.
Choosing the city and the home
Most of our NRI clients are deciding between Bangalore, Hyderabad and Chennai, usually based on family ties. Our comparison of the three cities sets them side by side on space, jobs, climate and the buying rules.
Within a city, a few things matter more for owners who live abroad:
- Low upkeep. Apartments in gated communities with a strong association are easier to manage from afar than standalone houses. Villas in managed communities, with security and maintenance contracts, are a good middle ground.
- Airport access. Homes in North Bangalore, the Shamshabad side of Hyderabad and the southern suburbs of Chennai make short visits easier.
- Rental demand. If you plan to let the home until you return, stay close to the office districts. Our Bangalore tech parks guide and HITEC City guide show where tenants look.
- Developer track record. When you cannot visit the site often, the developer’s history of delivering on time matters even more.
Homes our NRI clients often ask about

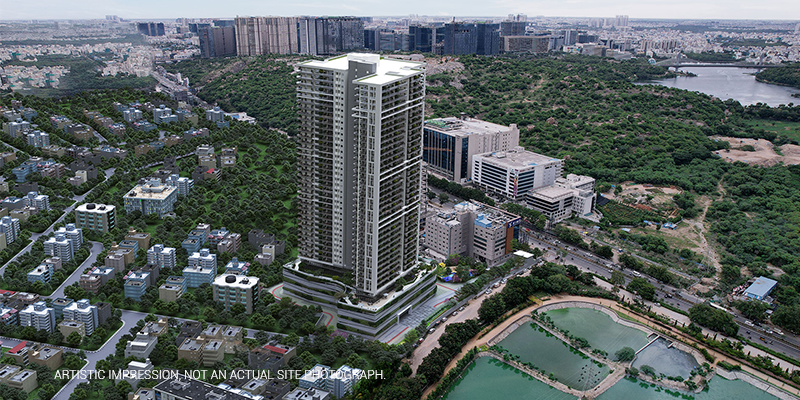
150 very large homes of about 5,000 to 7,750 sq ft on 2.4 acres, near the Financial District. Developer: Prestige.
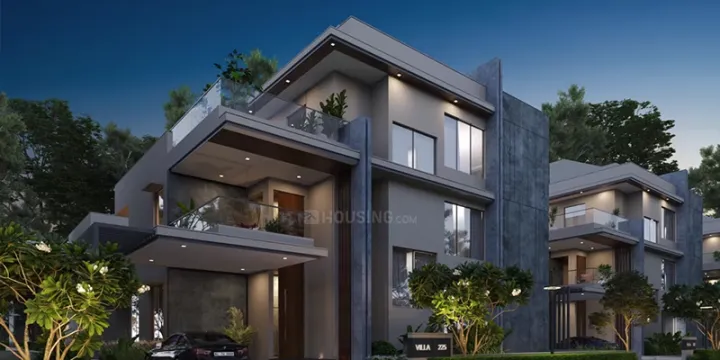
230 villas of about 3,950 to 5,750 sq ft on 46 acres, close to the airport.

180 homes on 5 acres in one of the city’s most established neighbourhoods. Developer: Sobha.

Large homes of about 2,500 to 6,500 sq ft on 17.5 acres, on the airport side of the city.

97 villas on about 6.3 acres on OMR, each about 2,280 to 2,510 sq ft. Developer: Casagrand.
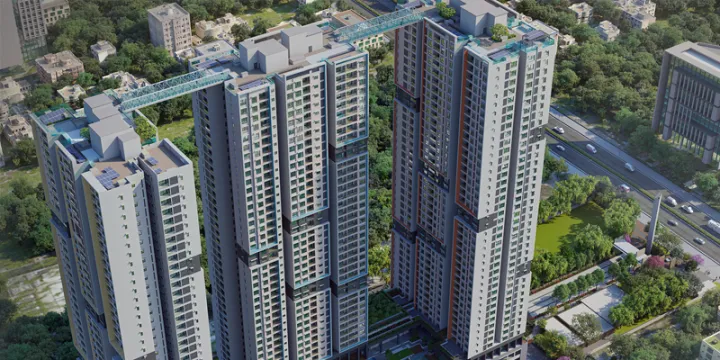
662 homes of about 1,700 to 2,600 sq ft in the middle of the OMR IT belt. Developer: Brigade.
Browse more on our Bangalore luxury apartments, Hyderabad villas and Chennai villas pages.
Buying an under-construction home from abroad
RERA has made buying off-plan far safer than it used to be. Developers must register projects with the state authority, keep a large share of buyers’ money in a dedicated project account, and publish progress updates. As an overseas buyer, use these protections:
- Search the project on the state RERA website (Karnataka, Telangana or Tamil Nadu) and save the registration page.
- Check the quarterly progress updates against the developer’s construction photos.
- Make payments only to the project’s designated bank account named in the agreement.
- Ask a family member or our team to visit at key stages, such as the structure being completed and before handover.
After you get the keys
Possession is where many NRIs feel most stretched. Plan for a snag inspection before you accept the home, the transfer of the khata, patta or tax records into your name, utility connections, and either a property manager or a trusted person to look after letting, maintenance and association dues. Many gated communities have rental desks and housekeeping services that make this easier.
A checklist for NRI buyers
- Get your PAN card and open or update your NRE and NRO accounts.
- Decide whether you want the option to repatriate, and pay through the matching route.
- Check the project’s RERA registration, approvals and the developer’s delivery record.
- Have a lawyer in India check the title, and a CA advise on TDS and tax.
- Arrange a specific power of attorney if someone will sign for you.
- Keep every remittance record, receipt and agreement in one folder, digital and paper.
- Plan who will manage the home after possession.
What we tell our clients
Buying a home in India from abroad is very manageable when you take it in the right order: pick the city and neighbourhood that fit your family, choose a developer with a strong record, get the payment route and the tax right from day one, and have someone you trust on the ground. Our team works with clients across time zones and can handle shortlisting, video walkthroughs and the paperwork with your lawyer and CA.
Frequently asked questions
Can an NRI buy property in India?
Yes. NRIs and OCI cardholders can buy residential and commercial property in India, with no limit on the number of properties. They cannot buy agricultural land, plantation property or farmhouses, though they can inherit them.
Can an OCI cardholder buy a flat or plot in India?
Yes, on the same terms as an NRI for residential and commercial property, including residential plots in approved, converted layouts.
Can NRIs get a home loan in India?
Yes. Most banks and housing finance companies lend to NRIs, with EMIs paid from NRE or NRO accounts or by remittance.
Do I need to be in India to register the property?
No. A person in India holding a specific power of attorney, signed abroad and stamped in India, can sign and register on your behalf.
Can I send the sale proceeds back abroad?
Generally yes, within limits: for up to two residential properties bought with foreign exchange, and up to USD 1 million a financial year from an NRO account, with the required documents.
Is TDS deducted when an NRI buys property?
When you buy from a developer or a resident seller above ₹50 lakh, you deduct a small TDS. If you buy from another NRI, you must deduct tax on their capital gains at higher rates. A chartered accountant should handle this.
More guides from our advisors- Chennai vs Bangalore vs Hyderabad: Where to Buy
- What Makes an Apartment Luxury? 7 Tests to Use
- What Is Neopolis? A Kokapet Guide for Home Buyers
By the Valuepersqft advisory team Property advisors across Bengaluru, Hyderabad, Chennai, Pune and Mumbai for 8+ years, working with 40+ developers and 500+ projects.
This article is general guidance, not legal or tax advice. Foreign exchange and tax rules change, and the Income-tax Act, 2025 replaced the 1961 Act from 1 April 2026; please confirm current rules with a chartered accountant, a property lawyer and our team before making a decision. Project details are taken from developer information and may change.
Talk to a Valuepersqft advisor
Honest, unbiased property advice. Call +91 6366229758, email support@valuepersqft.com or book a free consultation.
Offices: Whitefield, Bengaluru · Nanakramguda, Hyderabad · Manapakkam, Chennai · Kharadi, Pune.